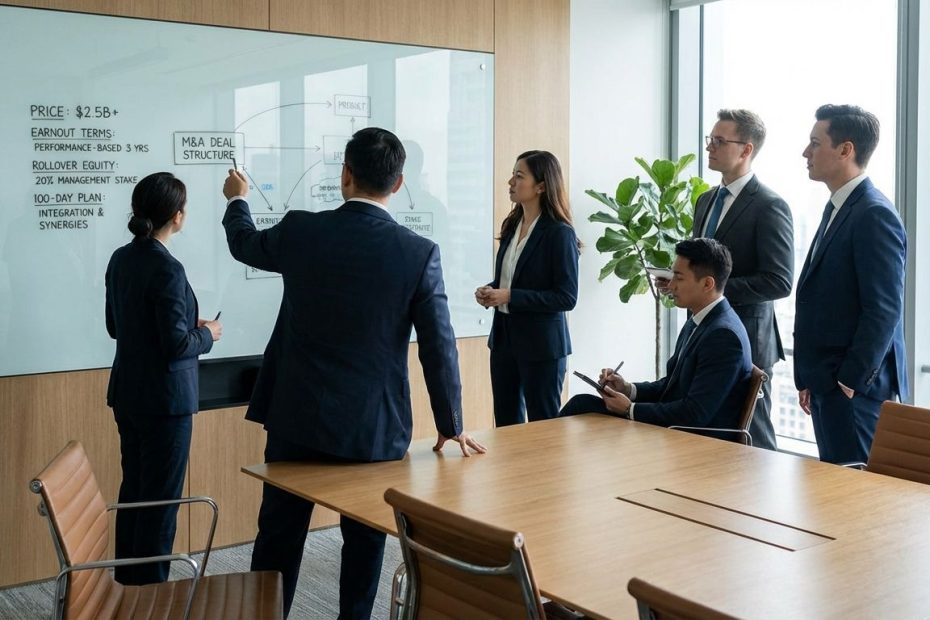
You create exponential outcomes in Mergers and Acquisitions (M&A) by mastering merger deal structuring—anchoring price to a quantified value thesis, allocating risk through enforceable mechanics, and driving disciplined post-close execution that converts projections into measurable financial performance.
This playbook gives you the deal-structuring moves that keep headline value from leaking into post-close disputes, missed targets, and avoidable dilution. You’ll get clear answers to the exact questions buyers, sellers, sponsors, and corp dev leaders keep asking, plus practical drafting and operating checkpoints that hold up under pressure.
How Do You Structure An M&A Deal To Actually Create Value (Not Just “Buy Growth”)?
Start by writing down the value thesis in numbers, not slogans. You need a short list of value levers tied to a baseline, a timing curve, owners, and what must change in the operating model to unlock those dollars. When that thesis is explicit, the term sheet stops being a collection of “market” positions and turns into a set of economic choices that either protect or weaken the thesis.
From a structuring standpoint, value is created when the contract makes good outcomes easier and bad outcomes harder. That means tying contingent consideration to the value drivers you can measure cleanly, limiting post-close price drift through well-defined adjustments, and preventing control games that quietly move economics from one side to the other. If the buyer can change policies, reallocate costs, or starve a business line during an earnout, the deal already contains the seed of its biggest dispute.
Operationally, value creation is also a timing contest. Market reactions at announcement do not decide the winner, execution over the next year does. The best deals protect the base business while accelerating capture of the planned value, with governance that connects initiatives to financial statements so leakage gets exposed early, not rationalized at quarter-end.
Earnout Vs. Rollover Equity: Which One Is Better, And When?
Earnouts and rollover equity solve different problems, so “better” depends on what risk is being priced and who can control the outcome. An earnout bridges valuation gaps by making part of the price conditional on post-close performance. Rollover equity keeps the seller invested, aligning incentives around the next phase of growth while reducing cash paid at close.
Earnouts work best when performance can be measured with limited interpretive judgment and when control rights during the earnout period are balanced. If the metric is Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA), you must tighten definitions around add-backs, allocation methods, and accounting policy changes, or the parties will relitigate the Profit and Loss (P&L) every quarter. If the metric is revenue, you still need rules for pricing, returns, channel mix, bundling, and contract timing, since those levers shift results without changing real demand.
Rollover equity works best when the seller is effectively underwriting the buyer’s plan and has conviction in the platform valuation, capital structure, and exit path. It becomes painful when the rollover is priced at a valuation multiple that embeds aggressive assumptions the seller cannot validate, or when preferred returns and distribution mechanics delay the seller’s participation in upside. Many high-functioning structures use a hybrid, modest earnout where measurement is clean, meaningful rollover where governance is clear, and a contract that prevents either side from “moving value” after signing.
What Earnout Terms Prevent Post-Close Fights And Value Shifts?
Earnout disputes almost always trace back to three root causes: unclear metric definitions, weak operating covenants, and poor information rights. Fixing those items upfront protects value and reduces the chance that the earnout becomes a multi-year argument that blocks integration decisions. Your goal is a structure where a neutral third party could calculate the earnout with minimal judgment, using agreed inputs and consistent policies.
Lock the metric and the math. Define the metric at the line-item level, specify permitted adjustments, and state the accounting principles and hierarchy that govern if conflicts arise. Add guardrails around extraordinary items, intercompany pricing, cost allocations, and any post-close reclassification that can change results without changing reality. When EBITDA is used, address compensation changes for seller-operators, one-time integration costs, and whether run-rate savings can be added back or must flow through actual results.
Then balance control. If the buyer controls budgets, hiring, pricing, product road maps, and customer terms, the seller needs operating covenants that prevent deliberate actions that depress the earnout metric. If the buyer needs freedom to run the business, the seller still needs defined “no sabotage” protections, timely reporting, and a clear dispute resolution path. Add practical features that reduce hard edges, tiered thresholds that pay partial amounts for near-miss performance, acceleration terms if the business is sold during the earnout window, and security mechanics when buyer credit risk is a real concern.
What Are The Most Important Purchase Price “Gotchas” (Working Capital, Escrows, Holdbacks, Indemnities)?
Headline price is marketing, net proceeds are math. Most unpleasant surprises come from the mechanics that convert the signed purchase price into cash at close and cash after the dust settles. Working capital true-ups, debt-like items, transaction expense definitions, and the survival structure of reps can swing value meaningfully, especially in deals where the seller expects a clean exit and the buyer expects a “fully scrubbed” balance sheet.
Working capital is the classic trap because it sounds objective but gets subjective fast. You need a clear target, a consistent calculation methodology, and a defined reference period that reflects how the business actually runs. If seasonality exists, a single snapshot date can be misleading, so the target must match the operating cycle. Tighten definitions for revenue recognition impacts on receivables, reserves, inventory valuation methods, accrual practices, and deferred revenue treatment so the true-up does not become a backdoor renegotiation of price.
Escrows, holdbacks, baskets, caps, and survival periods allocate risk, and they also change behavior. Sellers push for smaller escrows and shorter survival because cash certainty drives real-life outcomes. Buyers push for larger protection because unknowns are real, and diligence is never perfect. The “merger architect” move is to classify items by frequency and severity, then tailor protection to the actual risk profile, with clean separation between fundamental reps, general reps, and fraud. That reduces deadweight negotiation and keeps the agreement aligned with the value thesis, not generic templates.
Is Representation & Warranty Insurance (RWI) Worth It, And How Does It Change Negotiations?
RWI can be worth it when it buys speed, reduces seller tail liability, and avoids post-close distraction that derails integration focus. It changes negotiations by shifting the core fight from “how big is the escrow” to “what is excluded, what is the retention, and what diligence is required to bind coverage.” If the policy excludes the exact issues you worry about, the insurance becomes an expensive theater.
Use RWI when the process is competitive, the seller wants a cleaner exit, and the buyer wants coverage for breaches without holding a large escrow hostage. Expect underwriting to force discipline: tighter diligence, clearer disclosure schedules, and stronger internal documentation. That pressure can improve deal quality, but it can also slow signing if the team is not prepared, so timeline planning matters.
Negotiate the purchase agreement with the policy in mind. Keep reps structured so the insurer can underwrite them, ensure disclosure schedules are complete and not vague, and align materiality concepts between the agreement and the policy. Pay attention to known issues and forward-looking statements, which commonly sit outside coverage. The best outcome is an agreement that still stands on its own, with RWI acting as a risk transfer layer, not a substitute for clear drafting.
How Do You Model Rollover Equity So Sellers Don’t Get Diluted (And What Are People Confused About)?
Rollover equity confuses people because the economic result depends on where the rollover sits in the capital stack, the valuation used to price it, and the distribution waterfall at exit. Sellers often assume rolling a percentage of proceeds means keeping the same “ownership feel.” That is not how sponsor-backed structures work when preferred returns, leverage, and management incentive pools shape payouts.
Model the rollover like a new investment decision. Confirm the enterprise valuation used for the new entity, the net debt at close, and how much new money is going in alongside the rollover. Then map the equity classes, preferences, and incentive equity. If there is a preferred return to one class, then a catch-up to another, the seller’s payoff will not move pro rata with headline exit value until those thresholds are met. That timing difference can make a rollover look attractive on paper while underperforming in realistic outcomes.
Focus on three checkpoints. First, the entry valuation and whether the rollover buys into the platform at a fair price relative to risk and growth plan. Second, the terms of the instrument, common equity, preferred equity, options, profits interests, and any mandatory redemption or drag provisions. Third, the waterfall math, preferred return rate, catch-up percentage, and the point where distributions flip to pro rata. If those items are not crystal clear, the seller is signing up for blind risk, and the buyer is inviting future resentment that harms retention and performance.
What Does A “100-Day Plan” Look Like For Value Capture, And What Do Top Performers Do Differently?
A real 100-day plan is a quantified execution plan tied directly to the value thesis, with owners, milestones, and financial reporting that proves results. It covers Day 1 readiness, customer and employee retention measures, operating cadence, and a conversion path from initiatives to P&L impact. The operational goal is speed without breaking the base business, since revenue dips and talent loss erase the deal’s economics quickly.
High performers install governance that tracks the full value equation from initiative to financial statements, with visibility into leakage. They assign line leaders real ownership of targets and bake targets into budgets, not slide decks. They also set baselines before Day 1, so improvements are measured against frozen starting points, avoiding retroactive “baseline drift” that makes performance look better than it is.
Build the plan in structured sprints: define the hypotheses for value levers, validate with diligence data and clean team outputs, then commit only what is high confidence for external guidance and internal budgets. After close, keep the plan alive with versioning and a board-ready freeze point around the 100-day mark. This discipline reduces decision churn, improves accountability, and keeps teams from treating the integration office as the owner of outcomes.
How Do You Prevent “Value Leakage” After Signing Without Slowing The Deal?
Value leakage shows up in three places: pre-close drift, post-close economics drift, and execution drift. Pre-close drift comes from unmanaged interim operating periods, where performance slips, key people disengage, or customers sense uncertainty. Post-close economics drift comes from price adjustments, disputes, and terms that were not operationally workable. Execution drift comes from initiative overload, unclear ownership, and lack of link between initiatives and financial reporting.
Protect the deal during the interim period with tight covenants that are practical to operate. Avoid drafting that requires daily approvals for normal course actions, since that creates constant breach risk and slows the business. Define specific consent rights where real value sits, executive departures, pricing exceptions, capital expenditures over thresholds, major contract changes, then build a fast approval path so the operator team can keep running.
After close, prevent economics drift by aligning the contract with how finance and operations actually function. If the earnout depends on reporting, ensure the reporting can be produced reliably, on time, from systems that exist. If working capital will be tested, ensure the closing balance sheet process is resourced and the target methodology is set before signing. Speed comes from pre-baked templates and clear escalation rules, not from leaving key economic definitions to “later.”
How Do You Structure An M&A Deal For Maximum Value?
- Anchor price to a quantified value thesis
- Use earnouts only with tight metrics, covenants, reporting
- Model rollover equity with full waterfall, prefs, dilution
- Limit price drift via clear working capital, debt-like items
- Run a 100-day plan tied to P&L reporting
Build Your Merger Architect Playbook And Run It Deal After Deal
You win deals by designing the economics and the operating plan as one system. Put the value thesis into numbers, then make the agreement enforce those numbers through clean definitions, balanced control, and workable reporting. Use earnouts to price uncertainty, not to outsource disagreement, and treat rollover equity as an investment with real capital structure risk. Keep purchase price adjustments from becoming a second negotiation by tightening methodology before signing. Then execute with a 100-day plan that protects the base business, assigns line ownership, and tracks initiatives into financial statements so leakage gets managed early.
References
- McKinsey, “Post-close excellence in large-deal M&A.” ([mckinsey.com](https://www.mckinsey.com/capabilities/m-and-a/our-insights/post-close-excellence-in-large-deal-m-and-a))
- American Bar Association, “Shifting Value Post-Transaction.” ([americanbar.org](https://www.americanbar.org/groups/health_law/resources/health-lawyer/2025/shifting-value-post-transaction/))
- Umbrex, “Integration Value Thesis & Strategic Objectives.” ([umbrex.com](https://umbrex.com/resources/post-merger-integration-playbook-2025/integration-value-thesis-strategic-objectives/))
- Reddit, r/private_equity thread on preferred return and catch-up modeling. ([reddit.com](https://www.reddit.com/r/private_equity/comments/1j93lnw))

Alex Clug is a global entrepreneur and investor with 25+ years building and scaling ventures in medical robotics, telecommunications, mining, and private equity. He currently leads The Dolphin Group, advising early-stage and cross-border companies in robotics, fintech, natural resources, and other innovation-driven industries.